Showing posts with label Tessenderlo. Show all posts

Sunday, 2 July 2023

Dividends in May/June 2023


It's been a period with plenty of dividend payments which is always enjoyable especially now when I need to take out money instead of adding.

E.On paid out 204.00 € of which the German taxman kept 53.80 € and I was left with 150.20 € as cash on my broker account.

Intel paid out 44.75 €, USA tax office withheld 6.71 € and I was left with 38.04 € in cash.

TJX paid me 19.78 €, US withheld 2.96 € and I got 16.82 € on my broker account.

The next dividend payment I'm not really happy about. I wanted Luc to keep re-investing the earnings into the business or other endeavours for that matter!

Tessenderlo paid out 127.50 €, the taxman in Belgium kept 38.25 € and I got 89.25 € on my broker account.

IBM provided me with 38.34 €, tax withheld was 5.76 € and I got 32.58 € in cash.

BP paid me 49.46 € which arrived directly as cash.

Barratt paid out 59.36 € in cash.

Lloyds paid out 121.05 € in cash.

HSBC paid out 64.67 € in cash.

ETF EU paid out 301.16 € in cash

ETF S&P500 paid out 63.29 € in cash.

ETF All-World paid out 38.89 € in cash.

So a pretty good period!

Friday, 5 June 2020

Stock bought June 2020: Tessenderlo


As I previously mentioned it would either become more of Skanska or Tessenderlo. In the end I decided to increase my Tessenderlo investment.

I bought 80 more shares at a price of 27.60 € which gave a total cost of 2216.90 € including trading fee. I now have 170 shares in Tessenderlo at a total cost of 4297 € or 25.27€ per share.

To take a look at my current Stock Portfolio then please click on the link. The portfolio will however not be fully updated until the end of the month.


Friday, 8 May 2020

Analysis of Tessenderlo 2020


Company: Tessenderlo 

ISIN BE0003555639 | WKN 852064

Business: A Belgian chemical company. They currently have three operating segments : Agro, Bio-Valorization, Industrial Solutions and finally T-Power.

Active: 21 countries and 100 locations.

P/E: 11.4

To find out more concerning Tessenderlo then please go to analysis of Tessenderlo 2016.


The P/E of Tessenderlo good with 11.4 and the P/B is also good with 1.3 which gives a go from Graham. Earning to sales are so, so with 6% and the ROE is on the low side with almost 12% while the book to debt to book ratio is acceptable with 0.8.
In the last five years they have shown a yearly revenue increase of 1.9% which is not very good but still it is in the right direction and therefore gives us a motivated P/E of around 9 to 12 which means that Tessenderlo is today fairly valued by the market.
They pay out no dividends.

Future: Agriculture and let us call it upcycling, water treatment and energy. All if it has long term future as long as they can keep up with competitors.

Conclusion: Graham is ok with it and personally I think it is a good moment to pick up some more shares in Tessenderlo.

Wednesday, 2 May 2018

Analysis of Tessenderlo 2018


Logo of Tessenderlo 2018

Company: Tessenderlo 

ISIN BE0003555639 | WKN 852064

Business: A Belgian chemical company. They currently have three operating segments : Agro (~40% of revenue with liquid crop nutrients, water soluble SOP and crop protection), Bio-Valorization (~31% of revenue with gelatine, pharmaceuticals, body-care and bio-resources) and finally Industrial Solutions (~29% of revenue with pipes, water treatment and mining).

Active: 21 countries and 100 locations.

P/E: 57.5

To find out more concerning Tessenderlo then please go to analysis of Tessenderlo 2016.

Contrarian analysis of Tessenderlo 2018 with P/E, P/B, ROE as well as dividend.

The P/E of Tessenderlo is awful with 57.5 and the P/B is ok but not great with 2.3 which gives a clear no go from Graham. Earning to sales are too low with only 2% and the ROE is also horrible with 4% while the book to debt to book ratio is acceptable with 0.8.
In the last five years they have shown a yearly revenue decline of -1.5% which is not good and therefore gives us a motivated P/E of around 8 which means that Tessenderlo is overvalue by the market today.
They pay out no dividends.

Conclusion: Graham says no and so do I. Tessenderlo needs to start proving themselves before it will be interesting to push in more money there again. Now they have bought themselves, probably, a massive revenue increase that will most likely appear during the 2nd half of 2018 but they did that with cash and by overtaking debt. I will remain as a shareholder and have had until today's date a good development on that investment which has probably been more due to Luc than anything else. One day, not very far away, investors will want to see something concerning Tessenderlo.

Tuesday, 1 May 2018

Tessenderlo annual report 2017

Front page of Tessenderlo 2017 annual report
 For the report in full please click here and to see my previous summary then please visit Tessenderlo annual report 2016 and to find out more concerning Tessenderlo then please go to analysis of Tessenderlo 2017.

Below is the financial statement and it looks like a middle year. The earnings increased slightly compared to 2016 but the earnings was only 1/3 of last years. The invested and have now started up production of a liquid fertiliser that can be used both by households as well as by farmers. In the Q1 of 2018 they have also decided to buy out a energy producing plant that they previously owned 20% of for, as they mention, sustainability reasons as well as flexibility. When I calculated the P/E that they paid for that it was up around 20 which I find very expensive (they paid ~350 M €) especially since the earnings of that unit comes from a year when pretty much all energy producing companies have made nice profits. This makes me a little concerned. However... the reason for this investment was made on the leader Luc and his ability to find value so all will, I am sure, be good in the end.

Income statement of Tessenderlo 2017

Conclusion: Not a very good year for Tessenderlo but due to the latest deals I suspect that there will be a massive increase in revenue from the Tessenderlo Group as they now call themselves.

Wednesday, 15 March 2017

Analysis of Tessenderlo 2017


Logo of Tessenderlo 2017

Company: Tessenderlo 

ISIN BE0003555639 | WKN 852064

Business: A Belgian chemical company. They currently have three operating segments : Agro (~40% of revenue with liquid crop nutrients, water soluble SOP and crop protection), Bio-Valorization (~31% of revenue with gelatine, pharmaceuticals, body-care and bio-resources) and finally Industrial Solutions (~29% of revenue with pipes, water treatment and mining).

Active: 21 countries and 100 locations.

P/E: 15.1

To find out more concerning Tessenderlo then please go to analysis of Tessenderlo 2016.

Contrarian analysis of Tessenderlo 2017

The P/E of Tessenderlo is a little bit on the high side with 15.1 and the P/B is definitely too high with 2.5 which gives a no go from Graham. The earnings to sales are ok with 6% but one must admit that the ROE is pretty impressive with 16%. The book to debt ratio is also fully ok with 0.8.
The revenue growth rate is not very impressive for the last five years since it is at -5.7% which then gives us a motivated P/E of around 8 to 10 which means that Tessenderlo is today a bit overvalued on the market.
They pay no dividend at all which I do not like.

Conclusion: Tessenderlo would not be of interest to Graham as it is today with especially the P/B as it is because the P/E is ok. The ROE is also very nice but the fact that they do not pay a dividend is also disappointing. I will remain as a shareholder in Tessenderlo.

Tuesday, 14 March 2017

Tessenderlo annual report 2016


Front page of the Tessenderlo 2016 annual report


For the report in full please click here and to see my previous summary then please visit Tessenderlo annual report 2016 and to find out more concerning Tessenderlo then please go to analysis of Tessenderlo 2016.

In the financial statement below we see that the revenue was pretty much flat but the restructuring and cost cutting seems to start to have an impact on the result. We therefore ended up with almost 20% more in earnings which is good, good news!

Financial statement for Tessenderlo 2016


Conclusion: Tessenderlo still have along way to go before they start to make some serious money again but the from my point of view that period is getting closer and closer. I will remain as a shareholder in Tessenderlo.

Saturday, 1 October 2016

Chemical report Q2 2016


In the chemical group I decided to push in BASF, BP, Fugro as well as Tessenderlo. Fugro is indeed not a chemical company but it is very strongly influences by the chemical industry and especially then the oil industry that I decided that it makes more sense to bring them in here. If I will see a dramatic change in the business for Fugro then I will know that BASF and BP is once again taking off and start to see the end of the tunnel.

BASF


BASF, Q2, 2016, front page


For the report in full please go here and for the latest summary which was the BASF report Q1 2016 then please click on that link and to find out more about The Chemical Company then please visit analysis of BASF 2016.

In the financial statement below there is not much to be happy about. The revenue has definitely crashed for BASF and it is now down by -27% the only good part there is that they have tightened up their costs that are happily down by -33%.This year they additionally have not held a party for 0.5 billion € so we end up with almost 2.5 billion € in earnings which is pretty similar to the party year so it is not good but at least they are showing earnings.


BASF, Q2, 2016, financial statement


Conclusion: BASF is struggling and their oil and gas business is down on its knees with -86% in revenue. Disturbing enough also the Chemistry is down by -15% which really surprises me since that goes against my thoughts. I will of course remain as a shareholder in BASF.

BP

BP, Q2, 2016, front page


For the report in full please click here and to see the previous summary regarding BP report Q1 2016 or why not take a look at the latest analysis of BP 2016. 

In the financial statement below we can see how hard BP is still suffering. The revenue was increased for Q2 in comparison to Q1 2016 but still it is far from what it was back in 2015. We can see that Rosneft start to recover a little so the flow from associates have kicked up a little but still I do not really see the light in the end of this tunnel based on these figures. Th earnings are yet again a loss in the size of, for the half year, 2 billion USD. I do not know if it should be stated as being light in the end of tunnel but they have increased their spending on exploration... Let us see if any of that has gone to Fugro.


BP, Q2, 2016, financial statement


Conclusion: BP is still doing awful. Crashed revenue, crashed earnings and for us poor shareholders the cannibalising continues with paid out dividend and a strongly decreasing equity that follows. I understand why they do not stop it but sometimes one really should. I will remain as shareholder.

Fugro

Fugro, Q2, 2016, front page

For the report in full please go here and to see my previous summary then visit Fugro report Q2 2016 and to find out more about Fugro then please click on analysis of Fugro 2016.

In the financial report below things are not a rose garden for Fugro. Revenue has crashed from 1.2 billion to less than 1 billion €. They keep firing people and selling out not only vessels but also entire divisions. Right now they are eating up the few retained earnings that they had from the good years and we can even see that their backlog is dying. They very strongly emphasise that many customers are pulling back their contracts within the oil and gas industry. So that BP increased their exploration does not seem to have landed in the hands of Fugro.


Fugro, Q2, 2016, financial statement


Conclusion: Fugro is still not doing well and they will not until oil prices goes up much higher. They are cutting, cutting and cutting which is purely a matter of surviving which makes it very sad for me to watch as a shareholder. I should never have entered in Fugro but I will not sell them at this time.

Tessenderlo

Tessenderlo, Q2, 2016, front page

For the report in full please click here and to see my previous summary then please visit Tessenderlo report Q1 2016 and to find out more concerning Tessenderlo then please go to analysis of Tessenderlo 2016.

From the statement below we can see there has not been any large changes when one compares 2015 with 2016. The revenue is pretty much flat, costs have decreased ever so slightly and we end up pretty much the same earnings as we had in 2015 for the running six months.


Tessenderlo, Q2, 2016, financial statement


Conclusion: Tessenderlo made that jump up from disaster to back on track in 2015 and as of yet they have not managed to bring it to the next level of having increased revenue and earnings. I am sure that it will come soon enough and I do not mind if I have to wait another year for it. I will remain as a shareholder in Tessenderlo.

Conclusion Overall: The chemical sector is not doing very well. Most of them have dropped back in revenue and earnings and if you are a service company to that sector then you will have serious problems right now.

Tuesday, 3 May 2016

Tessenderlo report Q1 2016


Tessenderlo, Q1, 2016, front page

Tessenderlo arrived with their Q1 report which is not a proper report but more of a trading notification. Either way it is out there and the share price took a serious nose dive of I think around -7%. Is there a reason to be concerned?

Sunday, 21 February 2016

Analysis of Tessenderlo 2016


Tessenderlo, a Belgian chemical company

Company: Tessenderlo 

ISIN BE0003555639 | WKN 852064

Business: A Belgian chemical company. They currently have three operating segments : Agro (~40% of revenue with liquid crop nutrients, water soluble SOP and crop protection), Bio-Valorization (~31% of revenue with gelatine, pharmaceuticals, body-care and bio-resources) and finally Industrial Solutions (~29% of revenue with pipes, water treatment and mining).

Active: 21 countries and 100 locations.

P/E: 14.5

Saturday, 20 February 2016

Tessenderlo annual report 2015


Tessenderlo, annual, 2015, report, front page

Tessenderlo arrived with an ok report which made the share price increase by over 12%. Silly is probably the word I want to use for that kind of share price movements. What was then in it?

Friday, 30 October 2015

Tessenderlo report Q3 2015


Tessenderlo, Q3, 2015, report, front page

Tessenderlo, my Belgian chemical company with excellent managers, arrived with their Q3 2015 "report". The Q1 and Q3 reports are minimalistic so there will not be too much to say. The share price was dipping down to around 25 € during October but are now already up around 29 € again. Was there any good news in the report?

Sunday, 30 August 2015

Tessenderlo report Q2 2015


Tessenderlo, Q2, 2015, front page, report

The chemical company Tessenderlo arrived with their half year report last week and in between the desperation and fear regarding China and investors still not being able to keep the fingers away from the cookie jar so the share prices are jumping all over the place. This said... on the day of the release the share price dropped significantly.

Thursday, 14 May 2015

Tessenderlo report Q1 2015


Tessenderlo, Q1, 2015, front page

My only Belgium company, Tessenderlo, arrived with their Q1 "report" for 2015. Calling it a report is to go a bit too far because in the end it is one A4 paper if one would print it on both sides. This is one of the effects coming from their new major shareholder as well as... now.. alone ruling CEO, Luc Tack, who is the alone reason for why I made this investment. What was then on this piece of paper?

Wednesday, 8 April 2015

Analysis of Tessenderlo 2015


Tessenderlo, a Belgian chemical company

Company: Tessenderlo

ISIN BE0003555639 | WKN 852064

Business: A Belgian chemical company. They currently have three operating segments which unfortunately is not well described on the home page yet but are structured as such in their annual report for 2014. The first one is Agro (liquid crop nutrients, water soluble SOP and crop protection), Bio-Valorization (gelatine, pharmaceuticals, body-care and bio-resources) and finally Industrial Solutions (pipes, water treatment and mining).

Active: 21 countries and 100 locations (I could not find an update on this information even though I guess it is now less due to sale of business units as well as other cost cuttings).

P/E: 20.8

Tuesday, 7 April 2015

Tessenderlo annual report 2014


Tessenderlo, 2014, annual, report, front page

The report arrived and nothing much happened to the share price which has generally slowly but surely been climbing up in the last months. What was in it?

Wednesday, 11 February 2015

Stock bought February 2015: Tessenderlo


Tessenderlo, a Belgian chemistry company

Finally there was nothing else of interest so I could now top up my investment in Tessenderlo! The price I paid was acceptable even though it became higher than what I paid the first time and higher then if I would have joined in on the share emission in December.

In the end I bought 45 new shares at a total price, including fees, of 1059 € which means 23.53 € per share. In total I now hold 90 shares at an investment cost of 2080 € which gives me an average share price of 23.11 € (previous was 22.69 € and if I would have joined the emission I would have received the shares for around 21 € if I remember correctly). It hurts me much less then what I thought it would to average up on the share price and this I find to be good news for me in the future.

To find out more about why I bought Tessenderlo please visit Extra stock bought September 2014: Tessenderlo. If you want to find out more about the company then please click on analysis of Tessenderlo.

If you want to see my current Stock Portfolio then click on the link but the portfolio will not be fully updated until the end of the month.

Wednesday, 17 December 2014

"Dividend" from Tessenderlo: December 2014

Tessenderlo, a Belgian chemistry company

It is not correct to call it dividend, because it is a sale of the pre-emptive rights that I received and decided to forsake, but I have decided to call all given money from companies for the sake of simplicity dividend and I will report the money in the dividend page.

I received 45 rights and they were sold for 1.548527 € giving me a total of 69.68 € and I have to pay taxes in the size of 7.29 €, I must admit that I had forgotten the tax payment when I calculated the benefit of selling the pre-emptive rights in comparison to buying more of them so in the end I will re-calculate what actually would have been the most favourable way.

If you want to find out more about Tessenderlo then please go to the analysis of Tessenderlo.

To check out my current dividend payment history then please visit the Stock Dividends page which has now been updated.

Wednesday, 10 December 2014

End of year overview 2014


bear, hug, air

The end of the year is near and for that reason it is a good time to look over all the investments again. The reasons for why I bought shares have not changed since last year so for all the old stocks you can go to the previous report called End of year overview of my contrarian stocks 2013. The old companies will however still be brought up with how much value they have generated (share price * shares + dividend - trading fees) and if there has been any new lesson learnt then that will also be brought up.

Friday, 31 October 2014

Tessenderlo operating report Q3 2014


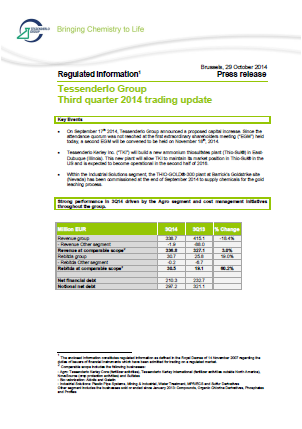
Tessenderlo, Q3, 2014, operating report, front page

The operating or trading report as they call it that they arrived with was a one and a half page report so the front page above is more or less all that were in it. Beautiful! I love to see when a company are cutting expenses in this way since that means to me that they are seriously going after costs cutting and are not only talking about it. The market responded with circulation around the +-0.5% during the day of publication.